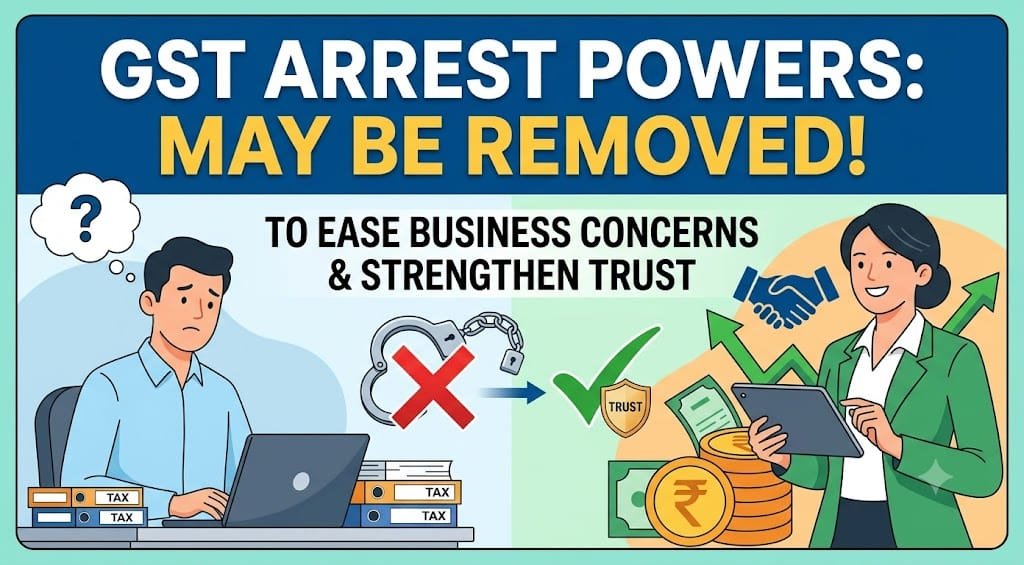
The Goods and Services Tax system in India may soon undergo an important change, as the government is considering removing the power of tax authorities to arrest people under GST laws. The proposal is expected to be discussed at the upcoming GST Council meeting on October 7.
The main purpose behind this possible reform is to create a more reassuring environment for traders, service providers, and companies, while continuing to deal firmly with serious and intentional tax fraud. According to reports, the Centre and states have held detailed discussions over the past eight to nine months to build agreement on this issue.
At present, GST officials can arrest a person in certain serious cases, such as fake invoices, fraudulent claiming of input tax credit, collection of tax without depositing it with the government, or issuing bills without actual supply of goods. Under Section 69 of the Central GST Act, such an arrest requires approval from the Commissioner, and the authority must have credible evidence rather than mere suspicion.
However, industry representatives have often argued that these powers were sometimes perceived as excessive and created anxiety among businesses, especially in sectors such as banking and insurance.
If the proposal is accepted, ordinary GST violations will continue to attract penalties, interest, and recovery of unpaid tax. But for intentional fraud, cheating, or serious deception, the authorities would follow the regular criminal justice process under the Bharatiya Nyaya Sanhita.
This means that genuine mistakes, documentation issues, or disputes over tax interpretation may be handled through legal and administrative procedures, while deliberate criminal conduct would still face strict action. The change is therefore being seen as a balanced step that protects honest taxpayers without weakening the fight against tax evasion.
The concern over arrest powers is not new. Even before GST was introduced in July 2017, several states had raised questions about whether tax officers should have such authority. In a GST Council meeting in December 2016, Maharashtra officials had pointed out that arrest and confiscation powers did not align well with the idea of ease of doing business.
A West Bengal minister had also noted that under the earlier VAT system, arrests were handled through the police rather than tax authorities. These long-standing concerns appear to have influenced the current proposal.
The scale of GST-related offences shows why the government has been cautious. Between 2021-22 and 2024-25, central GST formations registered 72,393 offence cases and made 887 arrests. Many of these cases involved fake identities, mule accounts, bogus bills, and fraudulent input tax credit claims.
The government has maintained that arrest provisions were meant to deter unscrupulous evaders and protect public revenue. Still, the proposed reform suggests that the administration now wants to draw a clearer line between civil tax non-compliance and criminal fraud.
This development is also part of a wider effort to make India’s tax system less intimidating and more predictable. Recently, the Central Board of Direct Taxes removed arrest and detention provisions from certain income-tax recovery rules with retrospective effect from April 1, 2026. If the GST Council approves the removal of arrest powers, Parliament may see an amendment during the Winter Session.
For businesses, the expected outcome is greater confidence, fewer fears of sudden action, and a tax system that encourages compliance through clarity rather than pressure.

